This marks the group’s inaugural integrated annual report subsequent to the company’s unbundling from Tsogo Sun and listing on the main board of the JSE on 12 June 2019.
This has undoubtedly been one of the most challenging and disruptive periods in our 50-year history and this instability is likely to continue for at least the next 18 to 24 months. However, we see these challenges as an opportunity to rethink the way we do things and we hope to emerge from this crisis as a more efficient, agile group.
In order to provide shareholders with meaningful, like-for-like analysis of the group’s performance, the pro forma financial information set out in Annexure 3 of the company’s prelisting statement issued to shareholders on 23 May 2019 has been used as the comparative set of results. Shareholders are referred to Annexure 4 of the pre-listing statement for the reporting accountants’ report on the pro forma financial information.
Digital copies of the pre-listing statement can be found on the group’s website at www.tsogosun.com/investors/circulars/2019.
REVENUER4.5 billion 2%
EBITDARR1.4 billion 9%
ADJUSTED EARNINGSR278 million 31%
|
QUARTERLY CONTRIBUTION TO 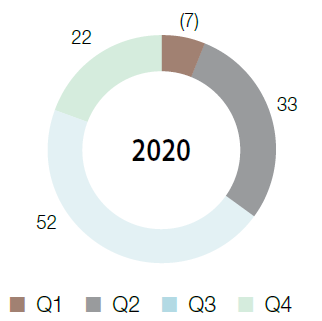
|
QUARTERLY CONTRIBUTION TO 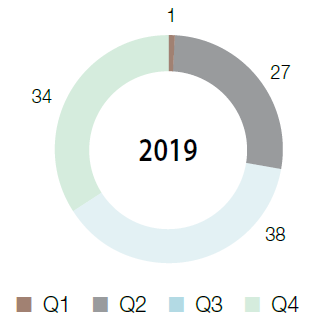
|
QUARTERLY PERFORMANCE REVIEW
The quarterly performance of key financial indicators as set out below reflect the seasonality of our business, which is weighted towards the summer season from October to March as well as the impact of COVID-19 and the subsequent national lockdown on the last quarter of the year in particular:
| Q1 Rm |
Q2 Rm |
Q3 Rm |
Q4 Rm |
Total Rm |
||
|---|---|---|---|---|---|---|
| Revenue | ||||||
| 2020 actual(1) | 961 | 1 112 | 1 229 | 943 | 4 245 | |
| Change on 2019 pro forma | 14 | 35 | (30) | (153) | (134) | |
| % change on 2019 pro forma | 1 | 3 | (2) | (14) | (3) | |
| Ebitdar | ||||||
| 2020 actual(1) | 206 | 353 | 452 | 296 | 1 307 | |
| Change on 2019 pro forma | (16) | (2) | (23) | (140) | (181) | |
| % change on 2019 pro forma | (7) | (1) | (5) | (32) | (12) | |
| Adjusted earnings | ||||||
| 2020 actual | (18) | 91 | 144 | 61 | 278 | |
| Change on 2019 pro forma | (22) | (16) | (9) | (78) | (125) | |
| % change on 2019 pro forma | * | (15) | (6) | (56) | (31) |
| (1) | Excludes the impact of the extension of the fixed and variable leases concluded over the InterContinental Sandton Towers, Sandton Sun and Garden Court Sandton City (collectively, the Sandton hotels) that became effective from 1 November 2019. The impact of these lease extensions is discussed under the income statement review below. |
| * | Percentage greater than 100%. |
Quarterly contribution to adjusted earnings
Trading during the first nine months of the financial year was impacted by the depressed local macro-economic environment, with demand by corporate and leisure groups as well as the transient traveller showing little sign of recovery.
The performance of the group’s offshore division was equally disappointing due to declining corporate and leisure activity in Maputo, government changes in Tanzania, a reduction in South African travel to Nigeria following the xenophobic attacks, as well as a significant retraction in business confidence in Lusaka following proposed amendments to tax legislation.
In addition to the decline in demand from corporate and leisure travellers, the Paradise Sun hotel in the Seychelles was temporarily closed following storm surges that caused damage to the public areas.
Subsequently, in response to COVID-19, the closure of the Seychelles borders and those of its key markets, France and Germany, has meant that this hotel only traded for six months of the year.
COVID-19 had a marked impact on the group’s fourth quarter trading with international demand retracting as early as the last week of February 2020.
The initial international travel regulations imposed by the President on 15 March 2020 and finally, the total ban on inter-provincial travel announced on 23 March 2020 as part of the nationwide lockdown resulted in a material reduction in revenues for the month of March, which is normally a peak activity month for the group.
The group’s entire portfolio in South Africa, Africa and the Seychelles has been deactivated with the exception of those hotels designated as quarantine facilities or as accommodation for essential service providers and persons awaiting repatriation.
SUMMARISED INCOME STATEMENT REVIEW
| 2020 Rm |
Pro forma 2019 Rm |
Note | ||||||
|---|---|---|---|---|---|---|---|---|
| Income | 4 475 | 4 389 | 1 | |||||
| Ebitdar | 1 352 | 1 488 | 2 | |||||
| Long-term incentive (‘LTI’) expense | (17) | (13) | 3 | |||||
| Property and equipment rentals | (84) | (208) | 4 | |||||
| Property and equipment rentals | (210) | (208) | ||||||
| Property and equipment rentals – IFRS 16 | 126 | – | ||||||
| Amortisation and depreciation | (348) | (306) | 4 | |||||
| Amortisation and depreciation | (289) | (306) | ||||||
| Amortisation and depreciation – IFRS 16 | (59) | – | ||||||
| Exceptional items | (1 669) | (581) | 5 | |||||
| (Loss)/profit before interest and taxation | (766) | 380 | ||||||
| Finance income | 40 | 38 | ||||||
| Finance costs | (400) | (269) | 6 | |||||
| Finance costs | (299) | (269) | ||||||
| Finance costs – IFRS 16 | (101) | – | ||||||
| Share of (loss)/profit of associates and joint ventures | (3) | 15 | 7 | |||||
| Income tax expense | (96) | (118) | 8 | |||||
| (Loss)/profit for the period | (1 225) | 46 | ||||||
| Non-controlling interests | 329 | (18) | 9 | |||||
| Attributable earnings | (896) | 28 | 10 |
1INCOME
Total income for the year of R4.5 billion (2019: R4.4 billion) ended 2% above the prior year, with a 2% growth in hotel rooms’ revenue and a 7% growth in food and beverage revenue. This growth was offset by a 7% reduction in property rental income and a 7% reduction in other income. Revenues were favourably impacted in the third quarter following the successful conclusion of the fixed and variable leases over the three Sandton hotels with effect from 1 November 2019, which together total 1 001 rooms and make up 5% of the group’s total rooms’ portfolio. In terms of the leases, after the deduction of management fees, 98% of hotel earnings accrues to the hotel owners as rent. It is worth noting that these leases are similar to those between Tsogo Sun Hotels and Hospitality. As a result, while the group consolidated the trading of these hotels on the income statement, the net impact on Ebitda is minimal. Excluding the impact of the Sandton hotels, revenue for the group’s base portfolio declined by 3% for the year ended 31 March 2020.
2EBITDAR
Despite strict cost controls during the year to counteract the above-inflationary increases in administered costs, including property rates and utilities, Ebitdar of R1.4 billion (2019: R1.5 billion) ended 9% down on the prior year. The decrease is primarily due to the shortfall in revenue as a result of the decline in demand which was further exacerbated by COVID-19. Excluding the impact of the Sandton hotels, Ebitdar for the group’s base portfolio declined by 12% for the year ended 31 March 2020. The overall group Ebitdar margin of 30% has declined by 4pp from the prior year.
3LTI EXPENSE
The long-term incentive expense in the income statement on the equity-settled incentive scheme of R17 million is R4 million up on the prior year pro forma charge of R13 million. The variance on the prior year is as a result of aligning the expense to the new equity-settled scheme that values the share-based payment (including dividend adjustments) by reference to the company’s share price adjusted for management’s best estimate of the appreciation units expected to vest and future performance of the group. The long-term incentive expense will increase by new grants made to employees and decrease by employee forfeitures.
4PROPERTY AND EQUIPMENT RENTALS
Property rentals, excluding IFRS 16 adjustments, at R210 million (2019: R208 million) are 1% up on the prior year. Amortisation and depreciation, excluding IFRS 16 adjustments, was R289 million (2019: R306 million), which is 6% down on the prior year. This is mainly due to year end residual value adjustments on the Hospitality property portfolio that is recognised as property, plant and equipment on a group level. The net pre-tax impact of IFRS 16 on the group’s income statement is a R34 million expense, with the majority of the adjustment relating to the leases over the SunSquare and StayEasy City Bowl, Garden Court Marine Parade and the Sandton hotels.
5EXCEPTIONAL ITEMS
Exceptional losses for the year of R1.7 billion (2019: R581 million) mainly relate to:
- Fair value losses on the revaluation of externally managed investment properties in Hospitality of R888 million (2019: R445 million)
- Property, plant and equipment impairments of hotels in South Africa and offshore totalling R716 million (2019: R94 million)
- Restructuring costs of R40 million (2019: R8 million) that includes retrenchment costs relating to the unbundling
- The impairment of the group’s investment in RBH of R17 million (2019: Rnil)
The majority of these impairments are due to management’s assessment of the negative impact of COVID-19 on forecast cash flows for the financial years ending March 2021 and March 2022, as well as volatility in the bond market and increased in-country risk assessments that have had a material impact on discount rates across the portfolio. In South Africa in particular, the risk posed by COVID-19 compounded by the ratings downgrade, saw the 10Y bond yield increasing by 1.9% from 31 March 2019 (8.61%) to 31 March 2020 (10.51%).
Refer to Note 16 of the consolidated financial statements for the sensitivity analyses relating to impairments and fair value adjustments.
6FINANCE COSTS
Finance costs, excluding IFRS 16 adjustments, of R299 million are R30 million above the prior year pro forma finance costs of R269 million due to the increase in debt to fund expansion and replacement capex including major hotel refurbishments during the year.
7SHARE OF (LOSS)/PROFIT OF ASSOCIATES AND JOINT VENTURES
The share of loss of associates and joint ventures of R3 million (2019: R15 million profit) declined by R18 million on the prior year primarily due to fair value losses on investment properties owned by IHPL.
8INCOME TAX EXPENSE
The effective tax rate for the year of 8.5% excludes the group’s share of losses of associates and joint ventures and is impacted by:
- Fair value losses that are not deductible for tax purposes on investment property in Hospitality
- The pre-tax profits attributable to the Hospitality non-controlling interests due to its REIT tax status
- The offshore tax rate differentials
9NON-CONTROLLING INTERESTS
Losses attributable to non-controlling interests of R329 million (2019: R18 million profit) increased by R347 million from the prior pro forma year, mainly due to the share of the R888 million fair value loss on investment property in Hospitality.
10ATTRIBUTABLE EARNINGS
| 2020 | 2019 Pro forma |
|||||
|---|---|---|---|---|---|---|
| Gross Rm |
Net of tax Rm |
Gross Rm |
Net of tax Rm |
% change |
||
| Attributable earnings | (896) | – | 28 | * | ||
| Loss on disposal of property, plant and | ||||||
| equipment (‘PP&E’) | 2 | 2 | 3 | 2 | ||
| Fair value adjustment of investment property | 888 | 888 | 445 | 445 | ||
| Impairment of PP&E | 716 | 664 | 94 | 67 | ||
| Impairment relating to RBH (associate) | 17 | 17 | – | – | ||
| Share of associates’ headline earnings adjustment | 41 | 41 | 10 | 10 | ||
| Non-controlling interest effects of adjustments | (500) | (500) | (181) | (181) | ||
| Headline earnings | 216 | – | 371 | (42) | ||
| Fair value adjustment on interest rate swaps | – | – | (2) | (1) | ||
| Restructure costs | 40 | 30 | 8 | 8 | ||
| Transaction costs | 3 | 2 | 32 | 32 | ||
| Pre-opening costs | – | – | 1 | 1 | ||
| Impairment of inventory | 2 | 2 | – | – | ||
| Fair value adjustment on RDI REIT plc (‘RDI’) | ||||||
| investment | 1 | 1 | – | – | ||
| Derecognition deferred tax | 30 | 30 | – | – | ||
| Share of associates’ exceptional items | 1 | 1 | – | (1) | ||
| Non-controlling interest effects of adjustments | (4) | (4) | (7) | (7) | ||
| Adjusted headline earnings | 278 | 403 | (31) | |||
Group adjusted headline earnings for the year at R278 million (2019: R403 million) ended 31% down on the prior pro forma year. The adjustments to the current year include the reversal of the post-tax and non-controlling interest impacts of the exceptional losses noted above. The number of shares in issue remained flat on the prior comparative pro forma year and the resultant adjusted headline earnings per share is 31% down on the prior pro forma year at 26.2 cents (2019: 37.9 cents).
LIQUIDITY, FUNDING CAPACITY AND COVENANTS
Free cash flow generated for the year of R484 million (2019: R414 million) increased by R70 million on the prior year, mainly due to the saving of finance costs on the treasury loan with Tsogo Sun Gaming. Cash outflows mainly consist of maintenance and expansion capex of R607 million group-wide, including major hotel refurbishments at The Westin for R70 million and Southern Sun Ridgeway in Lusaka for R73 million as well as the acquisition of Southern Sun Pretoria for R200 million.
CASH FLOW ANALYSIS FOR 2020 (Rm)
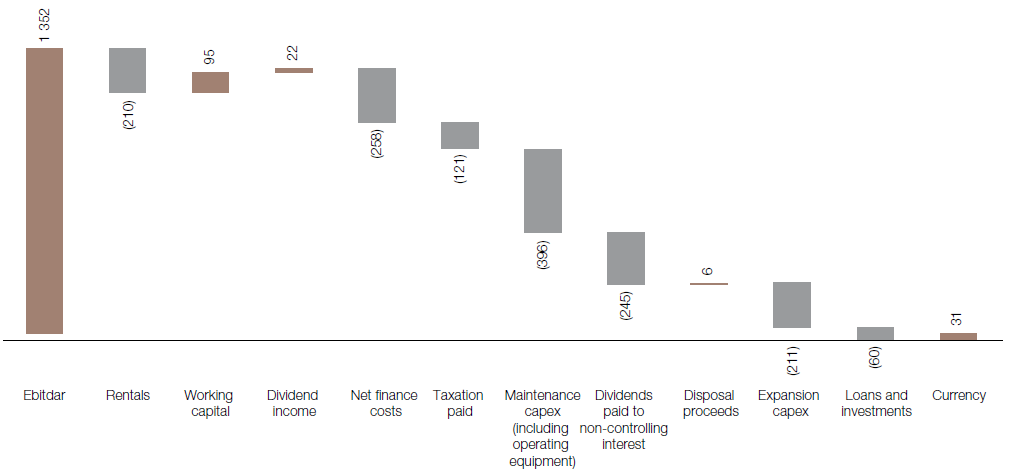
Interest-bearing debt net of cash at 31 March 2020 totalled R3.3 billion, which is R289 million above the 31 March 2019 balance of R3.0 billion, the detail of which is set out below:
| Share code |
2020 Rm |
2019 Rm |
||
|---|---|---|---|---|
| External debt – Offshore (US$-based) | TGO | 1 430 | 1 224 | |
| Prepaid borrowing costs | TGO | (3) | (5) | |
| External debt (Rand-based) | HPB | 2 550 | 1 959 | |
| Prepaid borrowing costs | HPB | (3) | (3) | |
| Gross IBD | 3 974 | 3 175 | ||
| Cash on hand | TGO | (431) | (117) | |
| Cash on hand | HPB | (291) | (95) | |
| Net IBD | 3 252 | 2 963 | ||
| Analysed as: | TGO | 996 | 1 102 | |
| HPB | 2 256 | 1 861 | ||
| Facility surplus including cash on hand | 1 662 | 831 | ||
| Cost of net debt – pre-tax (%) | 8.1 | 8.5 | ||
| – post-tax (%) | 6.1 | 7.2 |
The group’s liquidity and access to facilities are of paramount importance. As at 31 March 2020 the group was well within lender covenant requirements:
- Tsogo Sun Hotels’ leverage ratio (net debt:Ebitda) is 1.3 times against a maximum covenant requirement of no more than 2.5 times
- Tsogo Sun Hotels’ interest cover ratio is 12.2 times against a minimum covenant requirement of at least 3 times
- HPF’s leverage ratio (net debt:Ebitda) is 3.2 times against a maximum covenant requirement of no more than 3.5 times
- HPF’s interest cover ratio is 3.7 times against a minimum covenant requirement of at least 2 times
Lenders to both Tsogo Sun Hotels and Hospitality have approved the waiver of the September 2020 covenants, securing the group’s access to sufficient short-term liquidity facilities. Shareholders are referred to note 48 of the consolidated financial statements for further details.
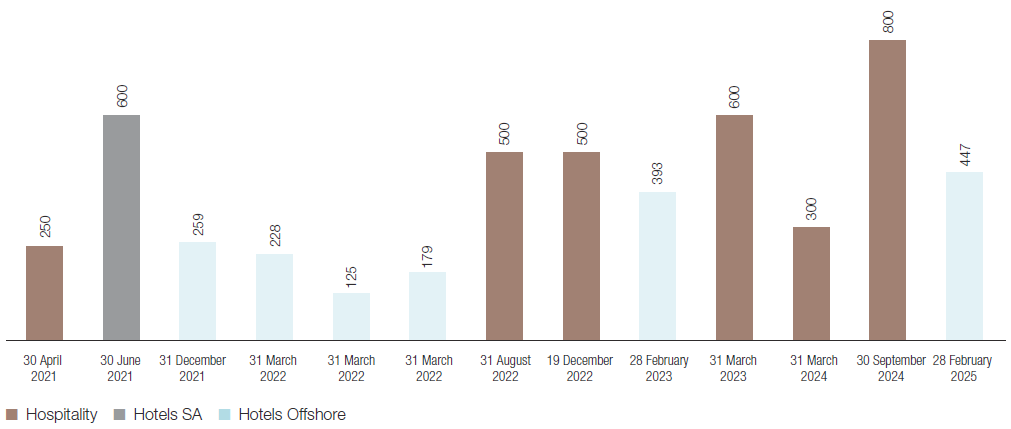
The average maturity profile of our debt is 2.9 years as at 31 March 2020. Subsequent to year end, Tsogo Sun Hotels increased its revolving credit facility from R300 million to R600 million and extended it by a year. The revised debt maturity profile is set out below:
DEBT MATURITY PROFILE (Rm)
GOING CONCERN
The consolidated financial statements are prepared on the going concern basis. Based on the cash flow forecasts, available cash resources and the other measures the group has taken or plans to take, management believes that the group has sufficient resources to continue operations as a going concern in a responsible and sustainable manner. As at 31 March 2020, the group has net cash and cash equivalents of R722 million (2019: R212 million). The group has R4.0 billion (2019: R3.2 billion) of interest-bearing debt (excluding capitalised lease liabilities) and access to sufficient undrawn short-term facilities to meet its obligations as they become due. In preparing the cash flow forecasts utilised to assess going concern, the impact of COVID-19 on the group’s operations and liquidity was considered. The directors have assessed the cash flow forecasts together with the other actions taken or proposed by management and are of the view that the group has sufficient liquidity to meet its obligations and to counteract the expected losses that may result from the COVID-19 impact on the group’s operations in the next financial year.
DIVIDEND
As outlined in the pre-listing statement, the group had intended to apply cash resources generated during the initial 15 months following the listing towards settling the offshore division’s Dollar denominated interest-bearing debt. Given the anticipated extended period of minimal revenue, the directors considered it prudent to retain cash resources to ensure that the group is able to navigate this difficult period until trading resumes. Accordingly, the directors have not declared a final cash dividend for the year ended 31 March 2020.
EVENTS OCCURRING AFTER THE BALANCE SHEET DATE
The directors are not aware of any matter or circumstance arising since the balance sheet date and the date of this report other than the matters disclosed in note 48 of the consolidated financial statements, all of which are non-adjusting events and have no impact on the financial results for the year ended 31 March 2020.
APPRECIATION
I would like to thank everyone involved in the year end process and in the preparation of this report. Your dedication and support in meeting our deliverables under the most difficult circumstances is greatly appreciated and speaks to who we are as a company.
Laurelle McDonald
Chief Financial Officer (CFO)
14 August 2020