The 2026 financial year was another strong year for Southern Sun,
characterised by record profitability, strong cash generation and
continued balance sheet strengthening. Total income increased by
9% to R7.2 billion, while Ebitdar grew by 12% to R2.4 billion and
adjusted HEPS increased by 19% to 90.1 cents per share (2025:
75.6 cents). The board declared a final dividend of 30.0 cents per
share, an increase of 20% on the 2025 final dividend of 25.0 cents
per share.
Free cash flow generation remained strong at R909 million for the
year, only R43 million lower than the prior year despite increased
capital expenditure of R600 million (2025: R450 million) and income
tax payments of R420 million (2025: R326 million). Capital
expenditure focused on major refurbishment projects at Southern
Sun Waterfront, The Westin Cape Town, Southern Sun Sandton,
Paradise Sun, Birchwood Hotel & OR Tambo Conference Centre,
Southern Sun The Cullinan, Mount Grace Hotel & Spa, Southern Sun
Mbombela, Southern Sun Newlands and Southern Sun Rosebank.
Strong cash generation enabled the group to continue investing in
the portfolio while funding dividend payments of R344 million and
share buybacks of R359 million. The group also settled its remaining
USD-denominated debt during the year and ended the financial
year in a net cash position of R86 million compared to net debt of
R266 million at 31 March 2025.
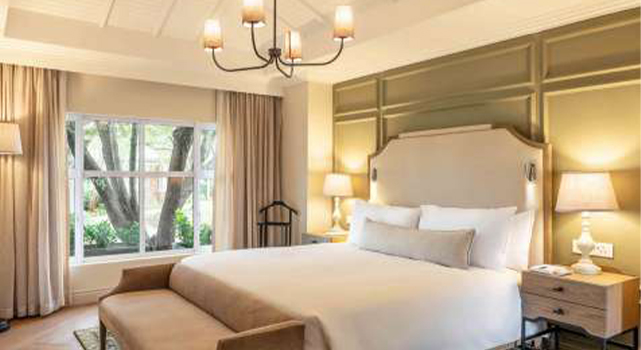
Mount Grace Hotel & Spa
This strong financial performance was supported by disciplined cost
management, continued demand recovery across the South African
market and the group's portfolio mix, notably its significant ownership
exposure to the Western Cape, which continued to benefit from
strong leisure, corporate and international inbound travel demand.
Combined South African and offshore hotel trading statistics,
excluding hotels managed on behalf of third-party owners and those
leased by third parties, are as follows:
| For the year ended 31 March |
2025 |
|
|
|
| Occupancy (%) |
62.9 |
60.8 |
| Average room rate (R) |
1 525 |
1 463 |
| RevPar (R) |
959 |
890 |
| Rooms available ('000) |
5 078 |
5 050 |
| Rooms sold ('000) |
3 194 |
3 071 |
| Rooms revenue (Rm) |
4 870 |
4 493 |
| frequentGuest loyalty expense (Rm) |
(94) |
(79) |
| Rooms revenue per the income statement (Rm) |
4 776 |
4 414 |
|
|
|
The group's operating costs remained well controlled, increasing by
8% during the year despite inflationary pressures, increased trading
activity and continued investment in technology and systems.
Employee costs increased by only 4%, while operating costs were
impacted by higher information technology expenditure associated
with the SAP S/4HANA implementation, increased property costs
arising from electricity tariff increases, municipal charges and waterrelated
costs, and higher distribution channel costs linked to increased
online travel agent activity. The suspension of loadshedding
contributed to lower diesel expenditure during the year, partially
offsetting utility cost increases.
The group generated Ebitdar of R2.4 billion (2025: R2.2 billion),
translating to an Ebitdar margin of 34% (2025: 33%). The margin
improvement reflects the group's operating leverage, disciplined cost
management and the strong performance delivered across the South
African portfolio, which more than offset the temporary impact of
refurbishment activity within the offshore portfolio during the first
half of the year.